
Investors are bracing for another volatile session as the market heads into Friday, with several key catalysts expected to drive price action across major indices. Analysts suggest that traders will be hyper focused on upcoming economic indicators and corporate earnings reports that could shift sentiment just before the weekend bell. The general mood remains cautious, as participants weigh recent inflationary data against the potential for shifts in central bank policy.
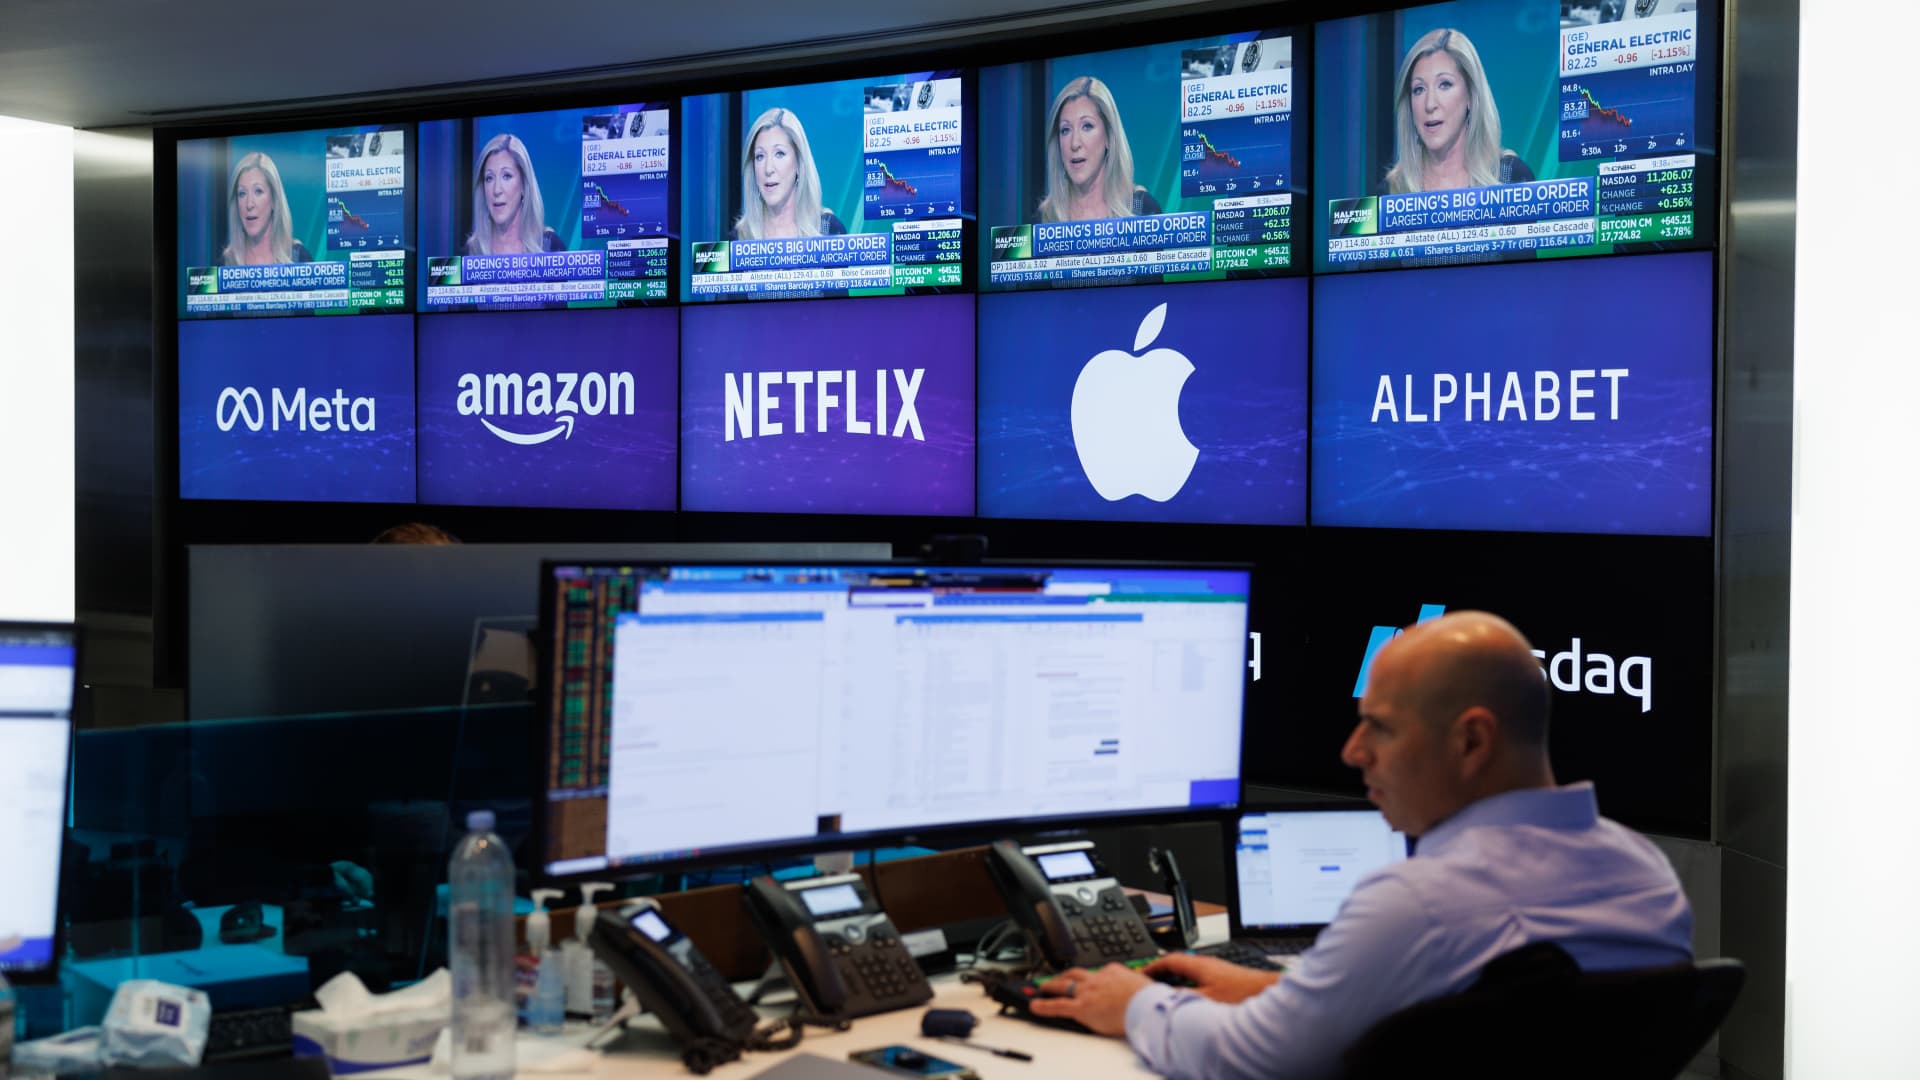
Much of the momentum is expected to center around a handful of heavyweight tech stocks whose quarterly results often dictate the direction of the broader S&P 500. If these industry leaders report stronger than expected growth or provide optimistic guidance for the coming months, it could spark a relief rally. Conversely, any sign of slowing demand or increased operational costs might trigger a sell off, dragging down smaller cap companies in their wake.
Beyond individual company performance, macro trends continue to play a decisive role in how portfolios are being managed. Traders are keeping a close eye on treasury yields and currency fluctuations, which have added an extra layer of uncertainty to international trade outlooks. As the closing bell approaches for the week, many institutional investors may look to hedge their positions or lock in gains from earlier wins throughout the month.
Ultimately, tomorrow’s movement will likely depend on whether positive corporate surprises can outweigh lingering fears about interest rates. While some bulls believe we are seeing the start of a sustainable upward trend, bears argue that current valuations remain too high given the geopolitical instability worldwide. For now, all eyes stay glued to the ticker as the financial world waits to see which side will prevail in Friday’s showdown.